Have a preferred lender?
They can cover part of your plan. Or all of it. Not a favor. They are buying the one spot in your follow-up that is worth something to them.
Feature your lender in the messaging.
Your database already has people wondering what they can afford. When one of them asks, somebody gets named.
Named in the conversation
A lead asks about financing. Substrait answers with your lender. Name, company, NMLS number.
Straight to their application
Their own online application page, not a generic one. It goes out when the lead asks for it.
Updated every week
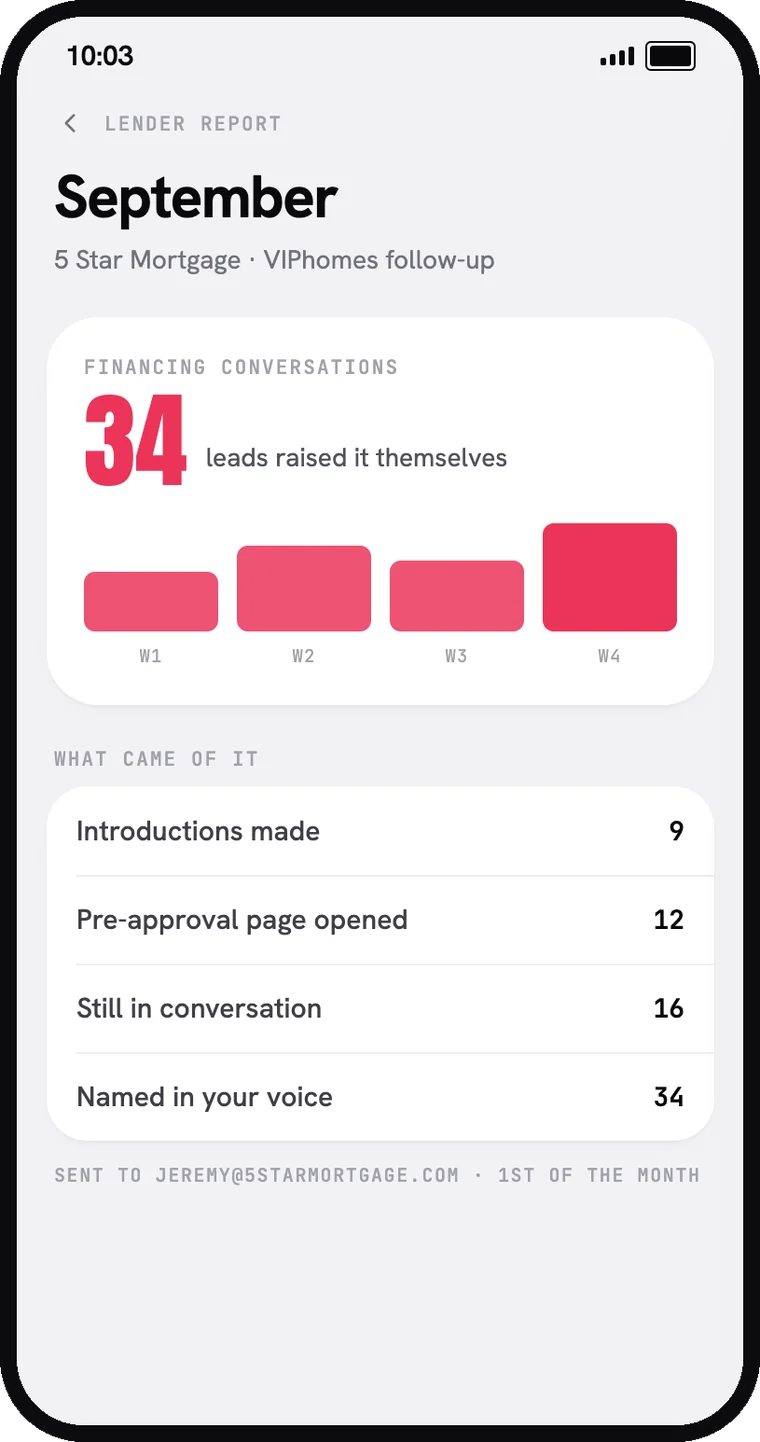
A Monday note with the week's numbers. They see what it did without having to ask you.
That is real marketing value, and it is what the agreement says they are buying.
Drag it. Watch your price move.
Real founding-member prices. Move the slider to whatever your lender is good for.
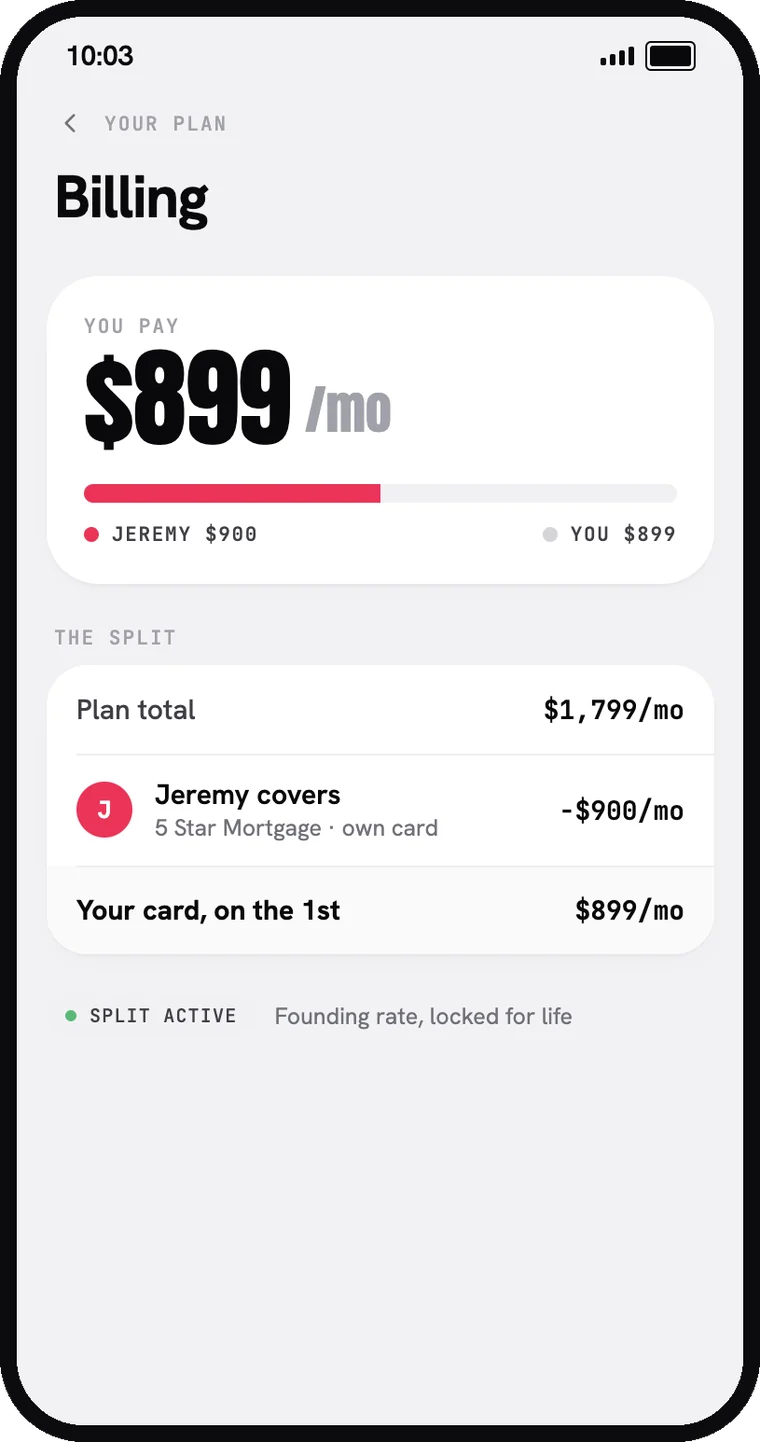
Founding-member rate, locked for life. Your lender is billed separately, on their own card.
A calculator, not a quote. Your lender sets their own number when they accept.
You both see the same split.
Their payment lands against your plan every month. Your own billing screen shows what they covered and what is left on your card, in plain numbers, with nothing to reconcile.
Four steps. None of them yours to chase.
Substrait writes the text. You send it from your own phone, to the lender you already work with.
Their page shows exactly what they get. They set the number, add their NMLS, and sign.
Their card, your card, same day each month. The split shows on your own plan screen.
Substrait names them when a lead raises financing. You choose how loudly they hear about it.
Two things this is not.
Real estate has a long history of arrangements that look like this and are not allowed to be. So this one is built not to be.
Pay us and we send you deals
Nothing is priced per lead, per application or per closing. Flat monthly, and that is the whole arrangement.
A consumer gets steered
Substrait answers the question it was asked. An introduction only happens when the lead asks for one.
Your lender attests the amount is fair market value for the marketing, and polices their own compliance. The agreement says so out loud.
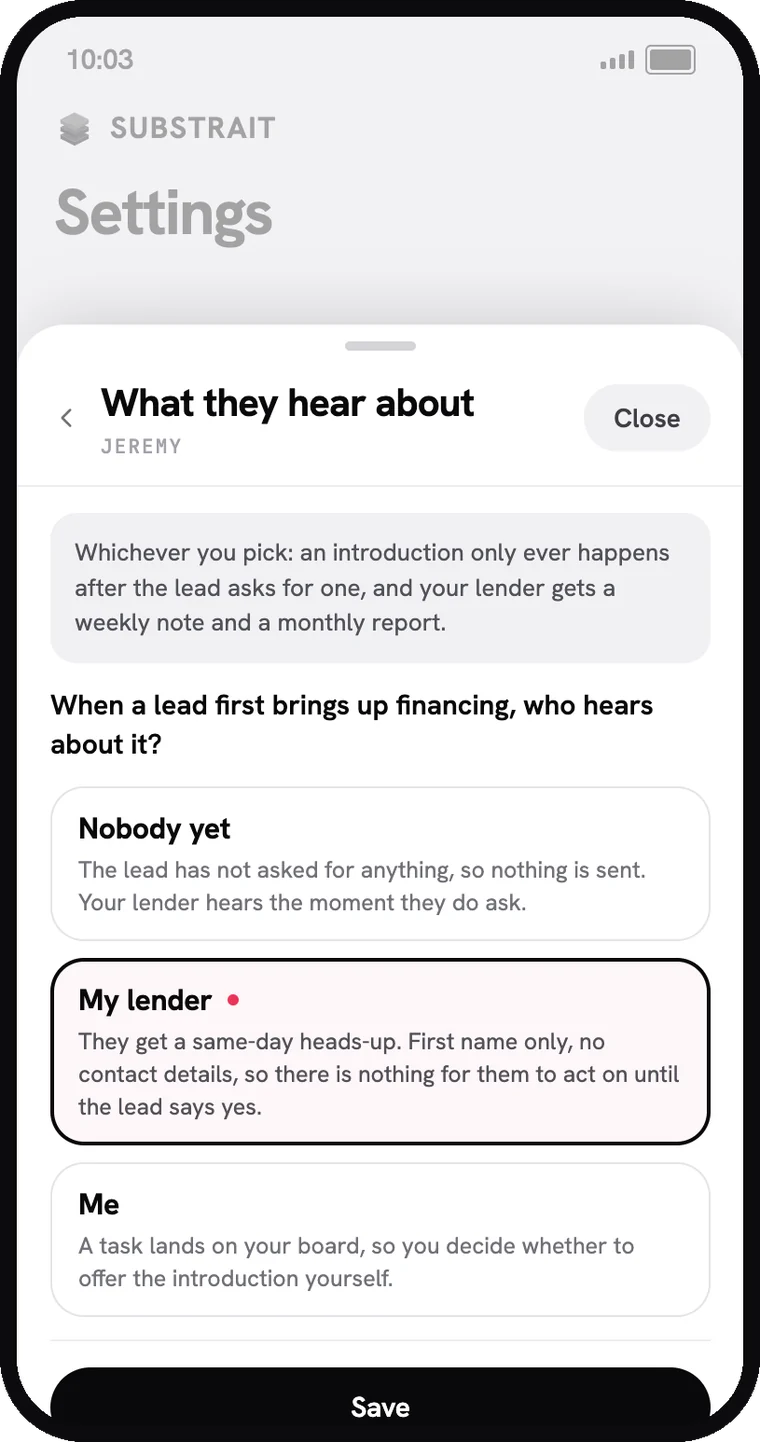
You decide what your lender hears.
Three settings, yours to change any time. Your lender can get a same-day heads-up with a first name and nothing else, a task can land on you instead, or they hear nothing until you say so. Whichever you pick, an introduction only happens after the lead asks for one.
Good for your agents. Good for you.
If you are the lender reading this, the pitch is simple. Your agent gets an AI working their whole database. You get named in the financing conversations it turns up.
Their database starts producing
Old leads, cold leads, past clients. All worked every day, not just the new ones. More live conversations for the agent you already back.
You are the named lender
Every time financing comes up, in the agent's own voice, with your company and NMLS number and your application page.
You can see what it did
A note every Monday and a report every month. Marketing you can actually measure, which is more than most of this costs you.
Ask your agent to send the invite from their Substrait settings. It takes them about ten seconds.
The questions everybody asks.
Does my lender have to cover the whole bill?
What does my lender actually get for it?
Is this a referral fee?
Who gets introduced to my lender?
What happens if my lender stops paying?
Can a lender pay for a real estate agent's CRM or AI tools?
I am the lender. How do I set this up with an agent?
Can I connect a lender without any money changing hands?
Try it before anybody pays for it.
Drop your number and start texting with Substrait right now. No setup, no card, no commitment. Sort the lender out later.